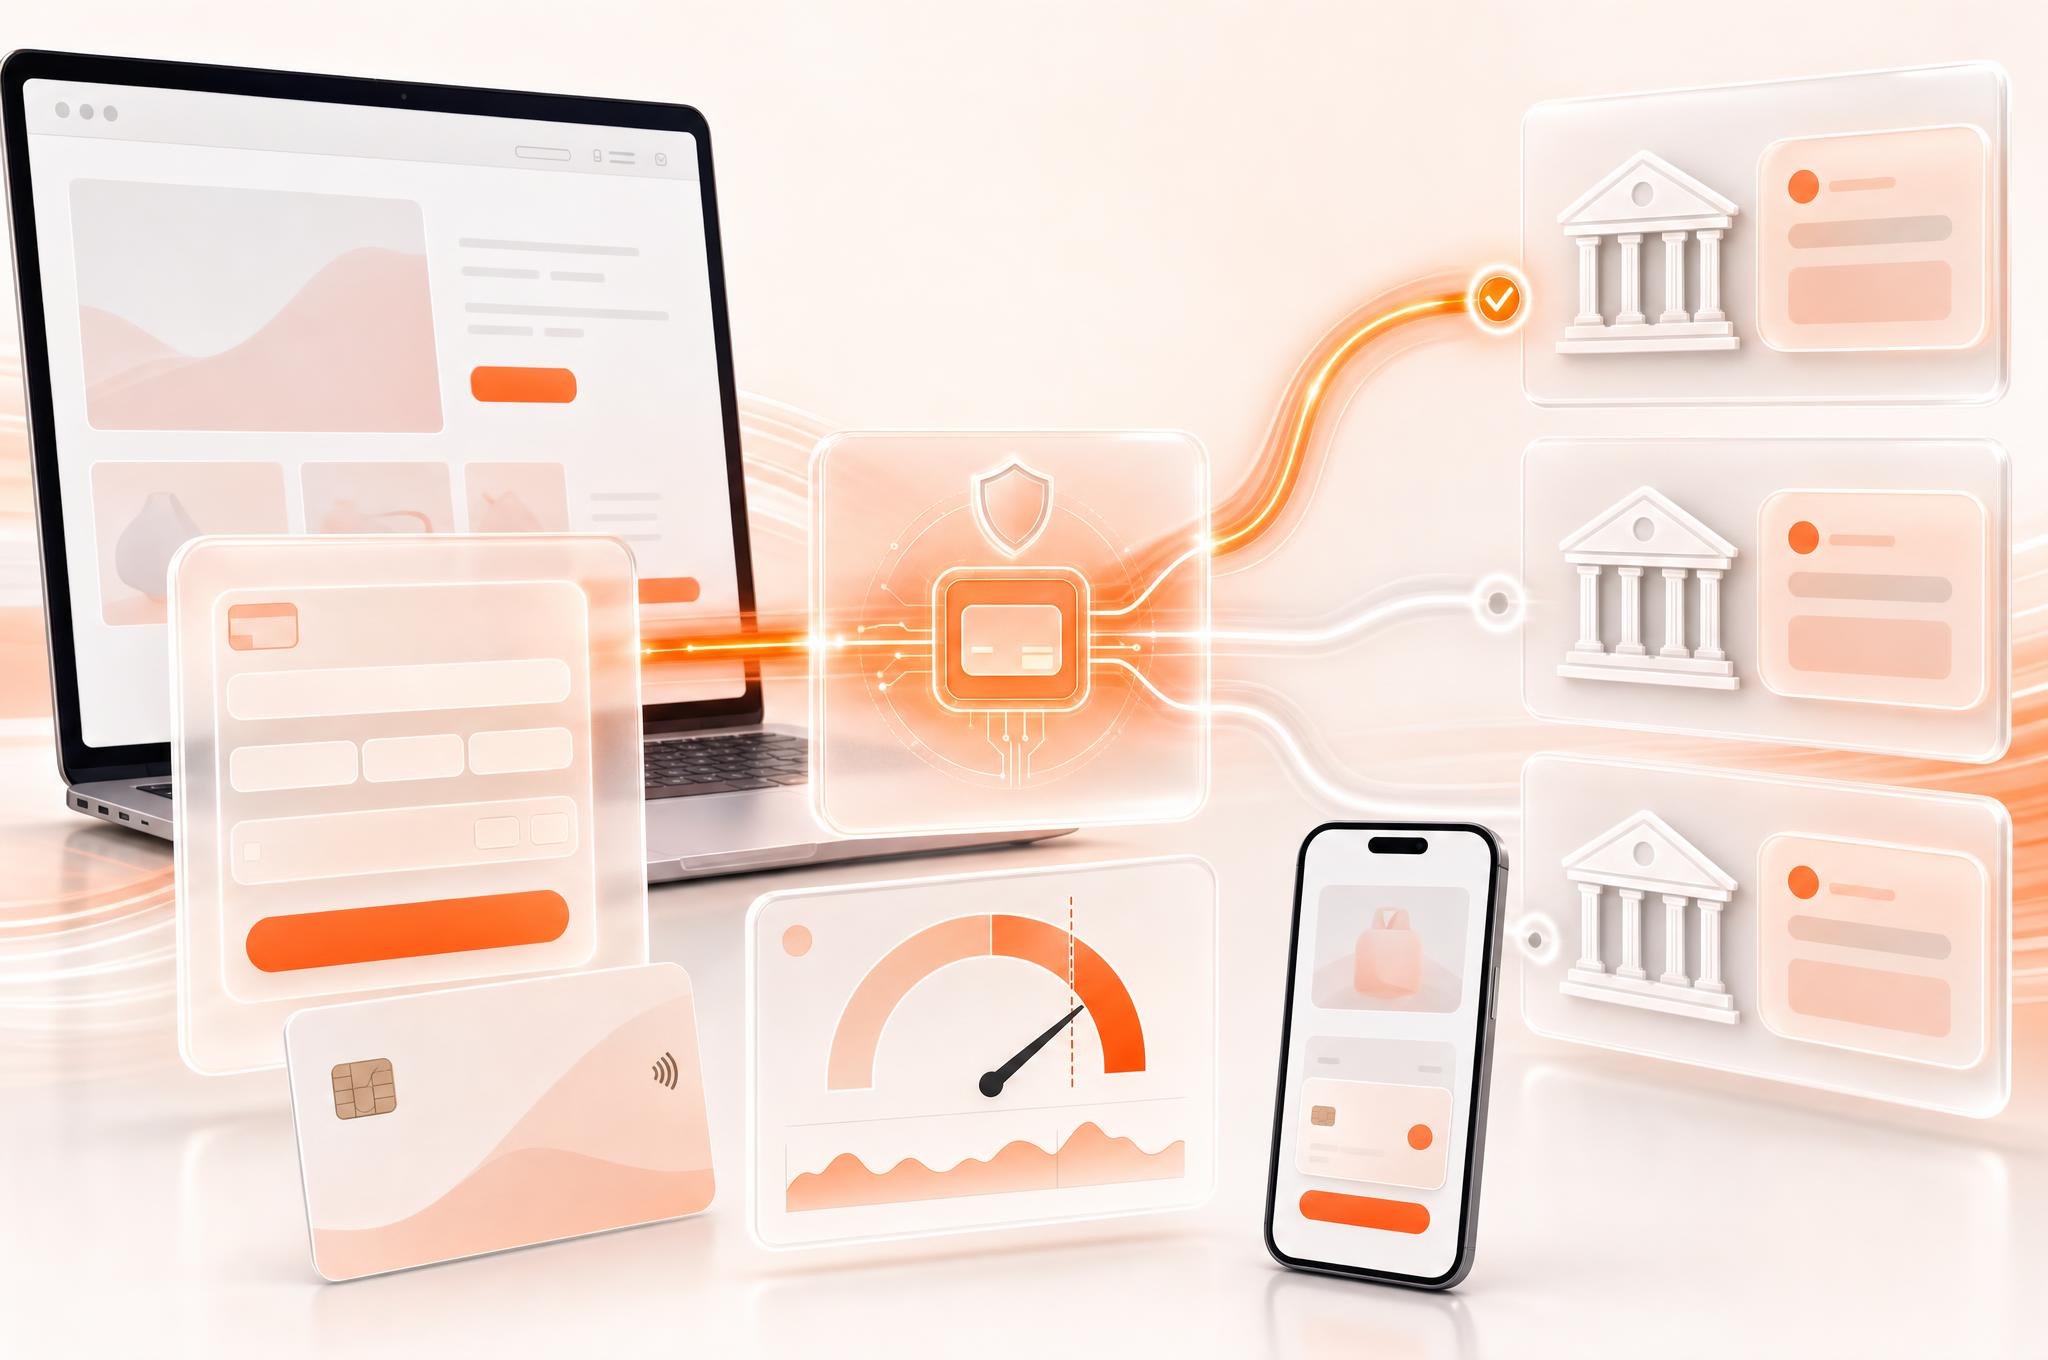
How PSPs and acquirers process high-risk card payments: which merchants count as high risk, who carries the liability, Visa VAMP thresholds, reserves and limits, the gateway features you need, multiple acquirers and the risks.
High-risk payment processing is card acceptance for merchants whose category, model or location brings more fraud, chargeback or legal exposure, under stricter scheme rules. This guide is for PSPs and acquirers that take such merchants and must set up the white-label payment gateway behind them.
What Is High-Risk Payment Processing?
High-risk payment processing is the same authorization, clearing and settlement flow as any card payment, run with more controls. The merchant is registered with the scheme, watched more closely, paid out with a reserve held back and routed through acquirers that accept its category. The difference lies in rules and limits, not in the message format.
You meet it from the PSP side. Your PSP software receives the payment, applies your rules and sends it to an acquirer that has agreed to take the merchant. Every decline, dispute and fraud report then counts against that merchant and against your portfolio with the acquirer.
Merchant onboarding is out of scope here. How you verify and underwrite a merchant before its first payment is covered in the guide to high-risk merchant onboarding. This guide starts at the first live transaction.
Definition
High integrity risk
Visa’s term for merchant categories that carry more legal and reputational exposure, such as betting or adult content. An acquirer must be approved by Visa to take them and must register each such merchant, as set out in the Visa Core Rules.
Which Merchants Are High-Risk?
A merchant is high-risk when its merchant category code (MCC), business model or market carries more fraud, chargeback or legal exposure. The clearest line is Visa’s list of high integrity risk MCCs for card-not-present payments. Your acquirer adds its own categories, such as future delivery and subscriptions, and higher-risk countries.
The table follows the Visa Merchant Data Standards Manual. It shows the categories that need registration, not the full list of what acquirers decline.
Examples of Visa high integrity risk MCCs for card-not-present payments
MCC
Category
Why acquirers treat it as high risk
7995
Betting, lottery tickets, casino chips, games of chance
Licensing differs by country; deposits are disputed as unauthorised
5967
Adult content and services
Reputational exposure and “friendly fraud” disputes
7273
Dating services
Recurring billing that customers do not recognise
5966
Outbound telemarketing
Sales pressure and high refund requests
5122, 5912
Drugs and pharmacies
Prescription rules and counterfeit risk
Source: Visa Merchant Data Standards Manual, October 2026
Forex and trading platforms are a frequent case for PSPs, and they need the same scheme checks. eComCharge has a separate page on iGaming and Forex PSPs. If your merchants are mostly retail, the low-risk PSP setup is the closer fit.
Who Carries the Risk?
The acquirer carries the scheme liability for every merchant it signs, including the ones you bring as a PSP. That is why it sets the reserve, the limits and the termination terms. The issuer decides whether to authorize and raises the dispute. You run the controls and pass the costs on to the merchant under your agreement.
Who does what in a high-risk card payment
Party
What it does
What it carries
Merchant
Sells, describes the charge, answers disputes with evidence
Chargeback amounts and fees, the reserve
PSP (you)
Routes, screens, sets limits, monitors merchants
Contractual losses, the acquirer relationship
Acquirer
Registers the merchant, settles funds, reports to the scheme
Scheme liability, monitoring programme fees
Card scheme
Sets rules, MCCs and monitoring thresholds
Rule enforcement, not losses
Issuer
Authorizes, reports fraud, raises disputes
Fraud losses on 3-D Secure authenticated payments, where liability shifts to it
Based on the Visa Core Rules and Visa Product and Service Rules
Liability for fraud can move. When a payment is authenticated with 3-D Secure, liability for fraud disputes generally shifts to the issuer. In the European Economic Area, strong customer authentication (SCA) is required under the PSD2 technical standards, with exemptions the issuer may refuse.
Card data is a shared duty too. If card numbers pass through your systems, part of the PCI DSS scope is yours, part sits with your gateway provider. A tokenization vault keeps raw card data out of your merchants’ systems and narrows that scope.
What Is a High-Risk Merchant Account?
A high-risk merchant account is an acquiring agreement with extra terms that protect the acquirer: registration with the scheme, a rolling reserve, volume and ticket limits, settlement delays and quick termination rights. The terms come from the acquirer’s risk policy. You enforce them on the merchant side and in your gateway.
Rolling reserve
A share of each payment is held for a set number of days, then released. Visa’s Acceptance Risk Standards treat it as the merchant’s property, held in a segregated account.
Transaction limits
Caps per payment, per card and per day. You set them in the gateway; see the post on setting transaction limits.
Settlement delay
The acquirer pays out later than for low-risk merchants, so chargebacks can be netted from funds it still holds.
Termination and MATCH
A merchant terminated for excessive disputes or fraud is added to Mastercard’s MATCH file, which other acquirers check before signing it.
Write the reserve and limits into your own merchant agreement with the same numbers your acquirer uses. If your terms are softer, the gap is your loss.
How Do Visa VAMP Thresholds Work?
The Visa Acquirer Monitoring Program (VAMP) divides a merchant’s card-not-present fraud reports and disputes by its settled transactions each month. Above the threshold, the merchant is identified and the acquirer must apply risk controls. For high-risk merchants this ratio decides whether you keep the account.
150 bps
Excessive merchant ratio in Europe, the US, Canada and Asia-Pacific from 1 April 2026
1,500
Minimum monthly count of fraud reports and disputes in those regions
50 bps
Acquirer portfolio “Above Standard” level; Excessive at 70 bps
Source: Visa Acquirer Monitoring Program fact sheet, 2025
The ratio counts fraud reports (TC40, the issuer’s fraud record) plus disputes (TC15) over settled transactions (TC05), as the VAMP fact sheet sets out. Disputes resolved through pre-dispute tools, which let the merchant refund or answer the issuer before a dispute is filed, are left out.
The 150 bps merchant threshold applies when the acquirer’s own portfolio is neither Above Standard nor Excessive. The acquirer level matters to you as a PSP. If your acquirer’s whole portfolio is above 50 bps, it is the one under review, and it will cut limits across all of its merchants, yours included.
Illustrative example
A merchant close to the line
Assumptions: a merchant in the EU settles 100,000 card-not-present Visa payments in a month. Issuers file 900 fraud reports and 700 disputes on them.
Fraud reports + disputes
900 + 700 = 1,600
VAMP ratio
1,600 ÷ 100,000 = 160 bps
Result
Above 150 bps and above 1,500 items: Excessive
Cutting 150 disputes with refunds before they are filed brings the merchant to 145 bps and below the minimum count.
What Does a High-Risk Payment Gateway Need?
A high-risk payment gateway needs controls you can change per merchant, card segment and acquirer without a release: routing rules, cascading, 3-D Secure rules, limits, blacklists and checks against payment history. The gateway applies your policy. The acquirer and scheme rules still define what is allowed.
Routing rules
Send each payment to the acquirer that takes its MCC, country and card type. See payment routing.
Cascading
Retry a soft decline on another acquirer, within the scheme limits on cascading payments.
3-D Secure per segment
Force authentication on risky segments and skip it where the risk is low, using a 3DS server.
Payment history
Check a card’s past chargebacks and failures before routing with SmartCheck signals.
Automated actions
Alert, blacklist or reject when a condition is met, with Action Rules.
Cascading needs care in high-risk traffic. A hard decline such as “stolen card” must not be retried anywhere, and the schemes limit how often a declined card may be retried, as the guide on scheme retry rules for cascading explains with the scheme sources. Set your cascade to soft declines only.
Routing and fraud rules belong in one engine. When Smart Routing evaluates anti-fraud and 3DS conditions in the same rule set, a payment cannot be screened by one policy and routed by another.
Why Use More Than One Acquirer?
Because a high-risk portfolio depends on the acquirer’s risk appetite, which can change overnight. A termination, a freeze or a new limit stops all volume routed to that bank. A second acquirer that already accepts your MCCs lets you move traffic instead of stopping it.
One acquirer
Termination stops all merchants at once
No fallback when the acquirer goes down
No bargaining power over reserve and limits
Two or more acquirers
Volume moves when limits are cut
Outages are routed around
Each acquirer sees a smaller share of risk
Moving a merchant is not free. The new acquirer registers it again, and stored cards must move with it. Keep tokens portable; the token migration case shows an acquirer switch with no customer impact. The full plan is in the multi-acquirer strategy guide.
Scheme rule
Do not hide a merchant from monitoring
Splitting a merchant across acquirers or changing its data to stay under VAMP is circumvention. Visa may charge the acquirer USD 25,000 per merchant per month and disqualify the merchant and its principals (section 12.5.3.2 of the Visa Core Rules).
Risks, and Who Does Not Need It
High-risk processing earns more per merchant but puts your acquirer relationships, cash and licence at stake. Each risk below has a control you can set before the first payment. If your merchants are mostly low-risk retail, you do not need this setup at all.
High-risk processing risks and how to reduce them
Risk
How to reduce it
One merchant pushes the portfolio over VAMP
Per-merchant dispute alerts well below 150 bps; reserve sized to the dispute rate
Acquirer terminates or freezes you
A second contracted acquirer; portable tokens
Merchant leaves with unpaid chargebacks
Reserve and settlement delay mirrored from the acquirer’s terms
Card testing on your checkout
Velocity limits, blacklists, forced 3-D Secure on new cards
Merchant sells where it is not licensed
Country rules in routing; block issuing countries outside the licence
Good to know
When a simpler option is better
If you sign a few high-risk merchants a year, refer them to an acquirer that specialises in the category instead of building controls for them. A dedicated setup pays off when high-risk volume is a core line of your business.
What to Check Before You Go Live
Before the first high-risk payment, confirm that your acquirer has registered the merchant and that every limit in its agreement is set in your gateway. Then test that each control fires. The list below is the minimum to check with your acquirer and your gateway team.
Go-live checklist for a high-risk merchant
The acquirer confirms Visa and Mastercard registration of the merchant and its MCC.
The reserve, settlement delay and limits match the acquirer’s terms.
Routing sends the merchant only to acquirers that accept its MCC and countries.
Cascading retries soft declines only.
3-D Secure rules are set for new cards and high-value payments.
Dispute and fraud alerts per merchant fire below the VAMP threshold.
A backup acquirer is contracted and tested with live traffic.
Review the merchant monthly against the same report the acquirer sees. A SmartCheck overview explains how history signals help high-risk PSPs act before the acquirer does.
High-Risk Processing with eComCharge
eComCharge is a white-label online payment gateway for PSPs and acquiring banks, with 14 years of processing high-risk traffic. More than 125 PSPs run their payment operations on it, high-risk and low-risk alike.
170+ connectors to acquirers, PSPs and alternative payment methods, with new ones in 1 week.
Smart Routing with routing, anti-fraud and 3DS rules in one engine, plus cascading.
SmartCheck signals such as chargeback and failed-transaction history as routing conditions.
An in-house 3DS server and a PCI DSS Level 1 card vault.
FinStatHub for custom analytics, reports and dashboards.
The acquirer failure case shows how traffic was moved when one acquirer failed. eComCharge pricing depends on the client’s specific needs: deployment model, volume, connectors and customisation. Contact sales for a quote.
Frequently asked questions
It is card acceptance for merchants whose category, business model or location brings more fraud, chargeback or legal exposure. The payment flow is the same as for any merchant. What changes is the scheme registration, the monitoring, the reserves and limits, and how carefully the PSP routes and screens each payment.
It is an acquiring agreement for a merchant in a high-risk category. Compared with a standard account it usually comes with scheme registration, a rolling reserve, transaction and volume limits, closer monitoring and stricter termination terms. The acquirer sets these terms because it carries the scheme liability for the merchant.
It is a gateway set up for traffic with higher fraud and dispute rates. It needs routing across several acquirers, cascading within scheme rules, 3-D Secure rules per segment, limits and blacklists, and history-based checks on cards and customers. The gateway does not take on the liability; it gives the PSP the controls.
Since 1 April 2026, a merchant in Europe, the US, Canada or Asia-Pacific is Excessive at a VAMP ratio of 150 basis points with at least 1,500 fraud reports and disputes a month. The ratio counts card-not-present fraud and disputes over settled transactions. Ask your acquirer which of its own limits apply on top.
Because chargebacks can arrive weeks after the merchant has been paid out. A rolling reserve holds back a share of each payment for a set period and then releases it, so money is there to cover late disputes. Visa treats the reserve as the merchant's property, held in a segregated account.
It can, but the whole business then depends on one bank's risk appetite. A termination, freeze or limit change stops all volume at once. Most high-risk PSPs contract a second acquirer that already knows the merchant categories, so traffic can move when the first one cuts limits.
eComCharge pricing depends on the client's specific needs: the deployment model, volume, connectors and any customisation. Acquirer fees and reserves are set by your acquirers, not by the platform. For a quote, contact the sales team.
Respectfully, the eComCharge Team
eComCharge develops and delivers the PCI DSS Level 1 certified white-label payment platform for Payment Service Providers and Payment Orchestration.
A practitioner's guide to launching a payment service provider: choosing a model, signing an acquirer, licensing, PCI DSS, platform choice, cost drivers and a 9-step launch plan.
How PSPs, acquiring banks and EMIs onboard high-risk merchants: which MCCs count as high risk, the KYB, UBO and sanctions checks EU law requires, underwriting and reserves, Visa registration and monitoring, what to automate and how to keep an evidence trail.
How a PSP protects itself from a sudden acquirer shut-off, outage or limit change: concentration risk, scheme and underwriting triggers, backup acquirers, portable tokens, volume split, an outage runbook, costs and who does not need it.
A guide to cascading payments for PSPs and acquiring banks: soft, hard and technical declines, which Visa response codes may cascade, cascade design, duplicate-charge prevention, 3DS, scheme rules, recovery KPIs and who should not cascade.
A guide for PSPs, banks and platforms on custom payment solutions: custom build vs off-the-shelf vs white-label, what can be customised, how a connector or payout flow is scoped and delivered, what drives cost and time, and the risks.
The four types of payment tokenization service provider for PSPs and banks, network vs gateway tokens, token portability and migration, PCI DSS scope, and the questions to ask before you choose.